Analysis
Visa Hits Record Highs as Earnings Approach
$409
25 Oct 2026, 13:48
Bullish

Join Minipip Academy and access free courses in investing, trading, economics, and more.
Sign Up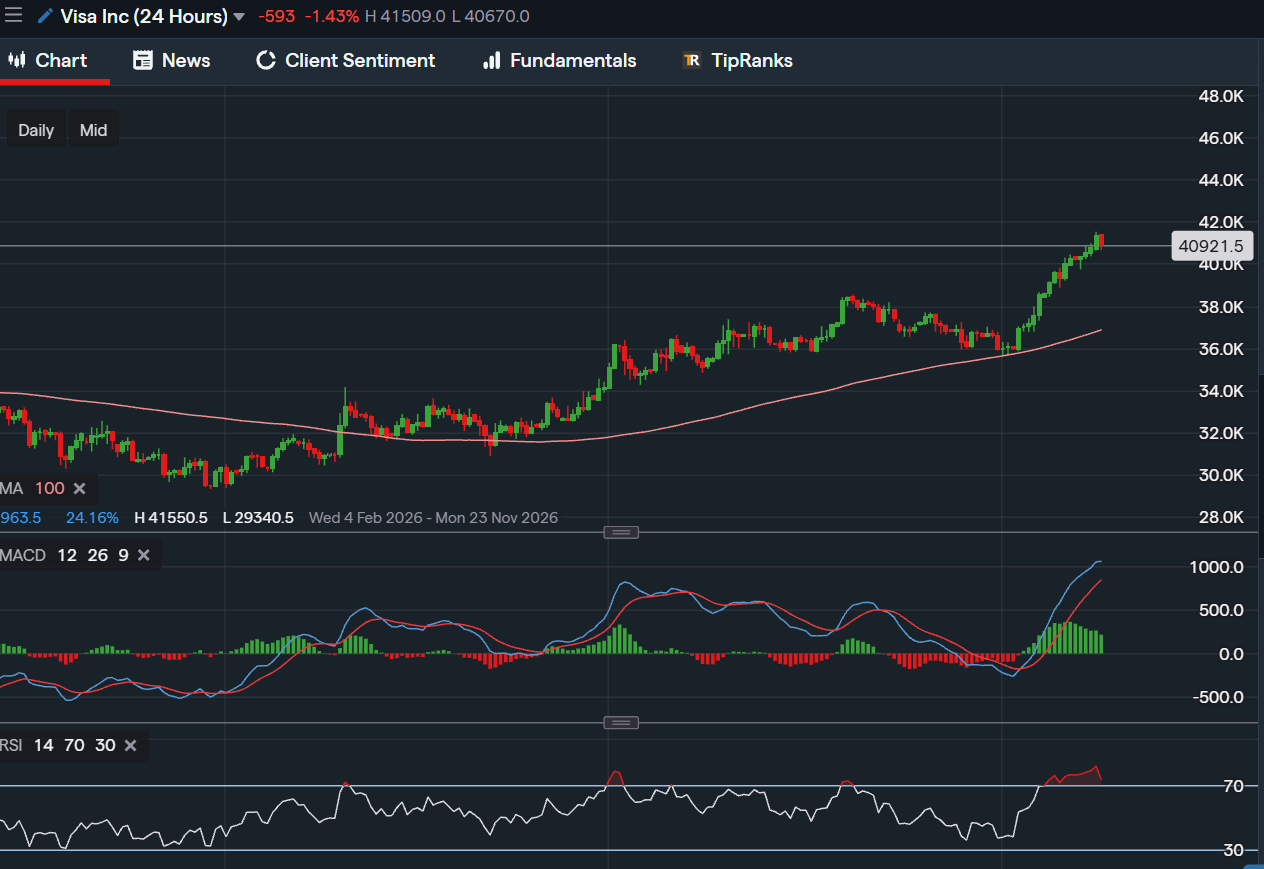
Visa Hits Record Highs as Earnings Approach


Visa has been one of the standout large caps of the autumn. After spending most of September drifting lower and testing its 100 day moving average around the $360 mark, the shares turned sharply higher in early October and have barely looked back. The stock is now trading around $409, having touched a new high near $415 this week, which puts it roughly 15% above where the rally began and close to 40% above the lows it set back in the spring.
The chart picture
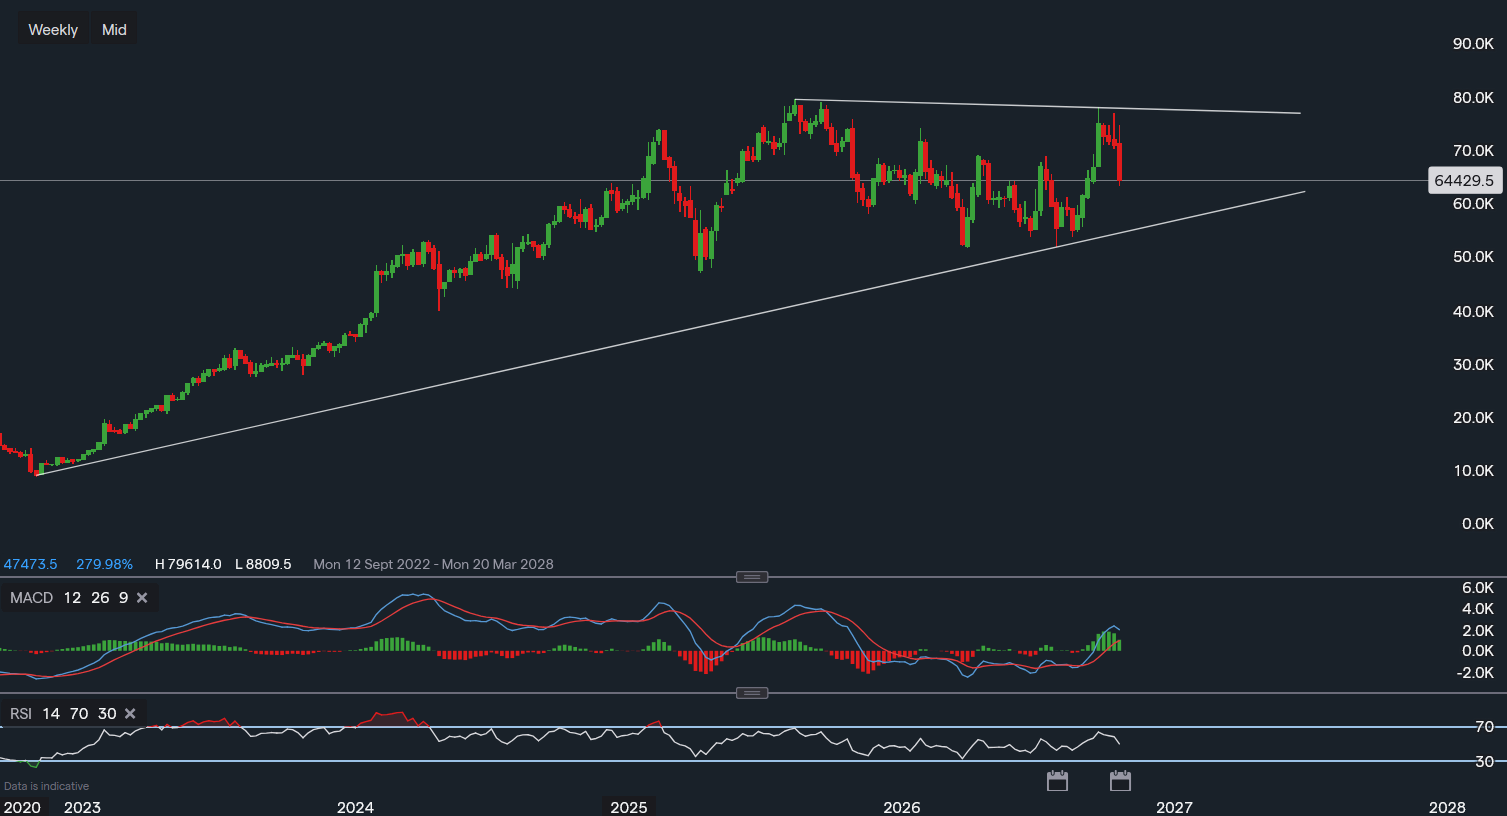
The structure of the move is clean. The 100 day moving average, currently sitting around $369, has been rising steadily since the summer and acted as a floor during the September pullback. That bounce was the launch point for the current run, and the stock has since cleared its previous peak in the $385 to $390 area, which had capped prices through August and September. That old ceiling now becomes the first meaningful support level to watch if the shares pull back. Below that, the moving average around $369 is the next line in the sand, and the area around $370 saw heavy trading activity, which could cushion any post earnings decline.
Momentum is where some caution creeps in. The RSI has been above 70 for well over a week, firmly in overbought territory, and the latest session shows it starting to roll over slightly. On its own that isn’t a sell signal, since strong trends can stay overbought for some time, but it does suggest the easy gains may be behind it for now. The MACD tells a similar story. Both lines are at their highest levels of the year, well above zero, but the histogram bars have been shrinking for several sessions, a sign that the pace of buying is slowing even though price is still climbing. Friday’s red candle, a drop of around 1.4%, fits that picture of a stock catching its breath.
The fundamentals
The business underneath the chart has been delivering. Visa has beaten analyst expectations on both earnings and revenue in each of its last four quarters. Its fiscal third quarter saw net revenue rise 14% to $11.6 billion and earnings per share climb 11% to $3.32, with quarterly payment volume passing $4 trillion for the first time in the company’s history. The quarter before that was even stronger, with revenue growing at its fastest pace since 2022. A key part of the story has been its value added services, which include things like fraud protection and data analytics sold to banks and merchants, and that division grew 34% last quarter.
That strength comes at a price. Based on the last four quarters of adjusted earnings, Visa trades on roughly 32 times earnings, a premium to the wider market that reflects its high margins and reliable growth. Using forward estimates the multiple drops to around 28 times, which looks more reasonable if the company keeps delivering. The dividend yield is modest at well under 1%, but Visa has a long track record of raising it, and the last increase was announced alongside its results this time last year.
What analysts think
Wall Street remains firmly positive. Visa holds a consensus Buy rating with an average price target of about $426, which leaves only around 4% upside from current levels. That gap has been narrowing all year as the share price has caught up with forecasts. More bullish voices exist, with RBC Capital holding a $466 target, and one chart based projection points towards $460. On the more cautious side, some analysts expect core sales growth to slow from around 14% to high single digits in fiscal 2027, and that outlook could matter more than the quarter itself.
Earnings on Tuesday
The big event is Visa’s fiscal fourth quarter and full year results, due after the US market closes on Tuesday 27 October. Analysts are expecting earnings of $3.43 per share on revenue of around $12.08 billion, and options markets have been pricing in a move of a little over 4% in either direction. With the stock at record highs and the RSI stretched, expectations are high, so a solid beat may already be priced in. Guidance for fiscal 2027 is likely to drive the reaction more than the headline numbers.
Summary
Visa is in a strong, well defined uptrend backed by consistently impressive results, but the shares look stretched heading into earnings. Overbought momentum and fading MACD readings suggest a pause or pullback would be healthy rather than alarming. If the stock does dip, the $385 to $390 zone and the rising 100 day moving average near $369 are the areas to watch for buyers to step back in. A strong set of numbers and upbeat guidance could carry it towards the $426 analyst target and beyond, while any disappointment on the outlook may see it give back some of October’s gains.
Tradable assets:
Min.Deposit:
Max Leverage:
FCA:

Rating:
 Earnings Calendar
 Economic Calendar
 VAT Calculator
 Tax Free Childcare Calculator
 Percentage Calculator
 Compound Interest Calculator
 Loan Overpayment Calculator
 Mortgage Calculator
 Credit Card Calculator
 Investing
 Economics
 Trading
 Technical Analysis
 Personal Finance
 Calculator