Analysis
Brookfield Tests Its Downtrend Ahead of Thursday’s Results
$4238
11 Nov 2026, 15:30
Neutral

Join Minipip Academy and access free courses in investing, trading, economics, and more.
Sign Up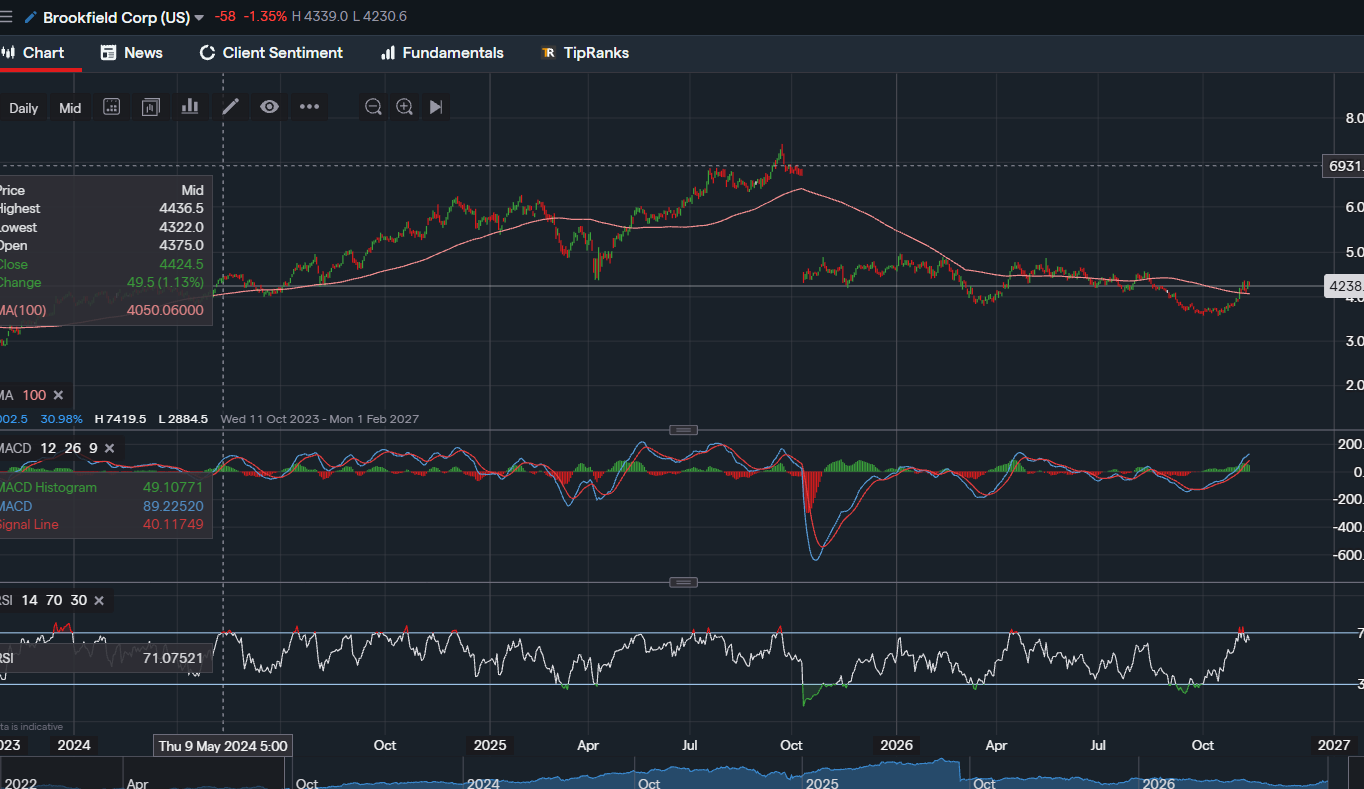
Brookfield Tests Its Downtrend Ahead of Thursday’s Results


Brookfield Corporation (BN): Market Analysis and Earnings Preview
Brookfield Corporation reports its third quarter results on Thursday. The stock goes into the report on the back of a strong rebound. It has climbed from its October lows around 3,600 to trade near 4,238.
Reading the bigger picture
On the longer chart, the share price looks like it collapsed in October 2025, falling from about 6,700 to about 4,500. That drop was not a sell off. Brookfield completed a three for two stock split, and every shareholder got one extra share for every two they held. The price per share fell while the value of their holdings stayed the same.
Since the split, the picture is less exciting. Through 2026 the stock has made a series of lower highs. It peaked near 4,950 in January, reached about 4,850 in the spring, then managed only around 4,550 in late summer. A trend line joined across those peaks slopes down and sits roughly in the 4,400 to 4,500 area right now. Price is pushing up towards that line just as earnings arrive, which makes this report a real test. A clean break above the line would be the first sign that the year long pattern of fading rallies is ending.
What the indicators are saying
The recent move has some genuine strength behind it. Price has climbed back above the 100 day moving average. That line had been falling steadily since late 2025 and is now starting to flatten out, just under the current price at around 4,100. Getting back above a falling average often signals that sellers are losing control.
The MACD backs this up. Both lines have turned up through zero, and the histogram has printed a run of green bars, so momentum is building on the upside. The RSI has pushed up to the 70 line, which is the classic overbought threshold. On its own that isn’t a reason to sell, because strong rallies often stay overbought for a while. Going into an earnings release, though, it means much of the good news may already be priced in. That leaves less room for disappointment.
What to expect on Thursday
The market is looking for distributable earnings of around $0.72 per share. That compares with $0.63 a year ago, so it would be growth of about 14%. Last quarter set a strong bar, with earnings up 15% and record fundraising of $77 billion.
The main focus will be the insurance business, which has grown quickly after the Just Group acquisition. Investors want proof that the extra size is turning into profit. Updates on carried interest will matter too, since that is the share of profits Brookfield earns when its funds sell assets at a gain. Last week Brookfield Asset Management, the listed fund manager Brookfield owns a large stake in, reported strong fundraising but trimmed its 2026 outlook. Investors will be watching for any knock on effect.
Valuation and analyst views
With a market value of around $105 billion, Brookfield trades at roughly 16 times its last twelve months of distributable earnings. That isn’t demanding for a business growing earnings in the mid teens. The dividend is small: $0.07 per share each quarter, a yield of well under 1%. Analysts are positive overall. The average price target is around $58, with the highest at $78 from Goldman Sachs and the lowest at $44 from Keefe, Bruyette & Woods. TD Cowen recently reiterated a Buy rating with a $61 target.
Key levels and scenarios
If Thursday brings a clear beat, steady buybacks and confident comments on carried interest, a move through the falling trend line near 4,450 would open the way back towards the 4,850 to 4,950 zone that capped the stock earlier this year. If the numbers or the outlook disappoint, the first support to watch is the 100 day moving average around 4,100. Below that come the March low near 3,800 and the October low around 3,600. History argues for caution here. After its last earnings release in August, the stock drifted about 10% lower.
The bottom line
Brookfield comes into its results with improving momentum and a business that keeps growing. Its share price, though, has spent a year failing to follow through on rallies. The indicators are supportive, but the RSI reading suggests the stock has already run hard. Thursday’s report will decide whether this rebound is a genuine change of direction or another lower high inside the downtrend. Waiting for the reaction and a confirmed break of the trend line is the more patient approach. Clear risk management matters either way.
Tradable assets:
Min.Deposit:
Max Leverage:
FCA:

Rating:
 Earnings Calendar
 Economic Calendar
 VAT Calculator
 Tax Free Childcare Calculator
 Percentage Calculator
 Compound Interest Calculator
 Loan Overpayment Calculator
 Mortgage Calculator
 Credit Card Calculator
 Investing
 Economics
 Trading
 Technical Analysis
 Personal Finance
 Calculator